
The useful number is not what a good gift ought to cost. It is what your life can comfortably let go.
To plan gifts on a tight budget, begin long before you begin shopping. Put the people and occasions you already know about on one page, choose an annual amount that will not follow you into next month’s bills, and divide that amount into small deposits. Then every invitation is no longer a fresh money emergency.
This is not a plan for making cheap gifts look expensive. It is a way to decide, calmly and in advance, where your money matters most – and to recognize when a card, a shared contribution, or simply not buying another thing is the sensible choice.
Begin with the whole year, not the next birthday
Open a calendar and mark the occasions you can reasonably predict: birthdays, graduations, weddings already announced, annual host gifts, religious holidays, and the December exchanges your family or workplace repeats every year.
Beside each one, write the person’s name – not “birthday gift.” A named list is much harder to inflate with imaginary obligations.
Separate expected gifts from possible gifts
Some expenses are nearly certain. Your mother’s birthday will happen. Your office may run its usual holiday exchange.
Other expenses are only possibilities: a colleague may leave, a cousin may become engaged, or a child may be invited to three parties instead of one. Give the first group individual lines and give the second group one modest buffer.
A buffer is not a pot of money waiting for an excuse. It is protection against having to borrow from groceries when ordinary life surprises you. If nothing comes up, the money stays yours.
Notice the expensive clusters
Circle months with several occasions. That is where planning earns its keep. A June graduation, Father’s Day, and two birthdays may each be modest, but together they can swallow a week’s flexible spending.
The answer is not necessarily to shrink every gift. It may be to begin saving in February, choose a group contribution for one event, or lower the ceiling on less personal occasions.
Choose an amount your life can afford to lose
There is no honest percentage that can see your rent, debt, medical costs, irregular income, or the number of people you care about. Start with what remains after necessities, minimum debt payments, and the savings you genuinely need.
Consumer.gov’s basic monthly budgeting approach is deliberately plain: list income, list expenses, subtract, then track what actually happens. Your gift budget comes from the money that remains – not from the amount other people appear to spend.
Set the annual ceiling before dividing it
Suppose $360 is the most you can comfortably use for gifts over the next twelve months. That is the ceiling for presents, cards, wrapping, postage, and the small costs that travel with giving.
It is not a challenge to spend all $360. For a wider way to balance meaning and cost, use this approach to meaningful gifts on a budget.
Protect the relationship from the price tag
People do not need identical amounts to be treated with care. Your child, a close friend, a neighbor, and a manager occupy different places in your life. Decide what each occasion calls for without using money as a ranking of affection.
When one particular gift is difficult to price, setting a sensible amount for an individual gift can help you separate closeness, occasion, and affordability.
If paying for a gift will make you nervous when the card bill arrives, the gift is already too expensive.
Turn the annual amount into a monthly gift fund
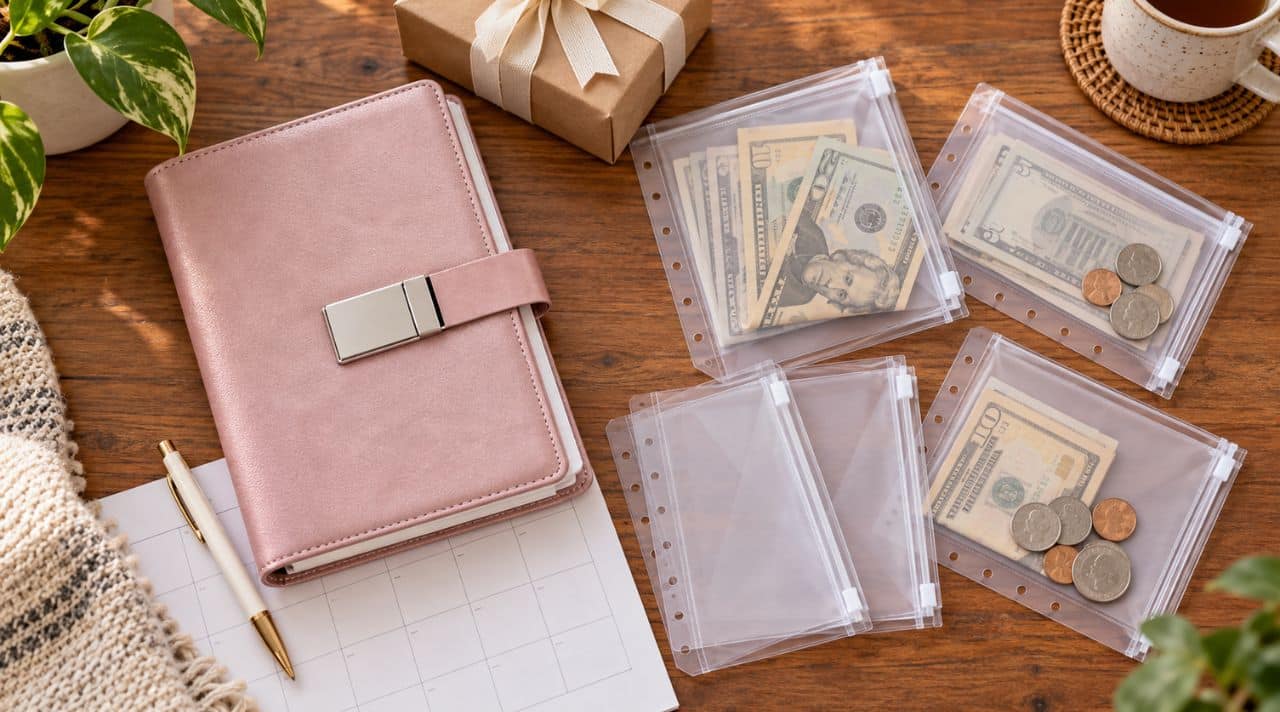
A gift sinking fund is simply money set aside a little at a time for gifts you know will come. It can live in a separate savings account, an envelope, or a budget category. The name matters less than being able to see the balance and not quietly spend it elsewhere.

Use the months you actually have
Annual gift budget ÷ number of saving months = monthly gift-fund transfer. A $360 annual budget divided across twelve months means transferring $30 into the gift fund each month. It does not mean buying $30 worth of gifts every month.
The money stays in the fund until an occasion arrives. After January and February, two $30 transfers create a $60 balance. Add another $30 in March and the fund reaches $90. A $40 birthday gift would leave $50 waiting for the next occasion.
| One possible $360 gift budget | Annual allocation | What it covers |
|---|---|---|
| Close-family birthdays | $120 | Several known birthdays |
| Graduation or milestone | $60 | One planned event |
| Year-end holidays | $130 | Gifts for named recipients |
| Cards, wrapping, and postage | $20 | Costs outside the gifts themselves |
| Unexpected occasion | $30 | One shared buffer |
| Annual total | $360 | The maximum for the whole year |
Monthly transfer: $360 ÷ 12 months = $30 moved into the gift fund each month.
This is an example, not a recommended allocation. A family with six summer birthdays will arrange the money differently. Someone who does not exchange holiday gifts may reserve more for one wedding.
The useful part is giving every dollar a purpose before a shop, sale, or social-media ad begins making suggestions.
Timing still matters. When a $120 expense arrives in March and the fund starts in January, twelve months are not available.
The real calculation is $120 ÷ 3 months, or $40 per month. When that amount does not fit, lower the planned cost or begin the fund earlier; the calendar does not accept optimistic arithmetic.
Make the transfer boring
If your income is regular, schedule the transfer just after payday. If income varies, move a smaller amount during lean weeks and more during stronger ones, while keeping the annual ceiling unchanged.
When the fund already contains the money, buying a birthday gift feels like completing a plan instead of damaging a month.
A holiday budget is only one version of this system. The same habit works for birthdays, weddings, and the ordinary occasions scattered through the year: set the money aside before the shopping begins.
Give every occasion a ceiling and a finish line
For each person or occasion, write four things: the date, the gesture you intend, the all-in ceiling, and the date by which the decision should be finished. “Aunt May – birthday – book or lunch – $25 total – decide by April 10” is more protective than “find something nice.” The second line can shop forever.
Spend according to the moment, not a fairness spreadsheet
A milestone may deserve more room than an ordinary birthday. A group farewell gift may need only a small contribution.
A wealthy friend does not need an expensive object merely because they can buy expensive objects themselves; something specific to their taste, accompanied by a real note, is often easier to receive.
When an occasion needs a tangible present but the line is small, look for meaningful gifts that fit a $10 limit. The aim is not to imitate luxury. It is to choose one useful or enjoyable thing and let it be complete.
Use shared giving to reduce pressure, not to enlarge the gift
For a teacher, manager, retirement, or large family gift, a group contribution can remove duplication and keep individual spending modest. Agree on a voluntary range before choosing the item. If the organizer finds something larger than the collected amount, the answer is not to chase everyone for more.
Count the quiet costs before calling a gift affordable
Add sales tax, delivery, wrapping, a card, batteries, ingredients, repairs, and any travel made only for the occasion. A $28 gift with $12 shipping is a $40 decision.
A homemade basket may be inexpensive when you already own the supplies; it may be surprisingly costly when you buy six ingredients, a new jar, ribbon, and postage.
Put delivery inside the same ceiling
When someone lives far away, decide whether your stated limit includes delivery – and it should. A smaller, lighter gift sent on time can be more thoughtful than a larger bargain followed by rushed postage.
Before buying, set aside money for delivery so the final checkout screen does not rewrite the plan.
Stop when the budget reaches zero
If the gift fund is empty, do not borrow from rent, groceries, emergency savings, or a credit card balance you cannot immediately pay. Change the form of the gesture or skip the purchase. That is not a failure of generosity; it is the budget doing the job you gave it.
This article is about planning money, so it will not turn into a long list of no-cost presents.
When there truly is no money available, move to gift ideas that cost absolutely nothing rather than forcing a purchase into a month that cannot hold it.
Keep the plan alive with three small words
You do not need a complicated budgeting app. A note on your phone or one sheet of paper can hold the truth:
| Person or occasion | Planned | Spent | Finished? |
|---|---|---|---|
| Sam’s birthday | $30 all-in | $27 | Yes |
| June graduation | $60 all-in | $64 | Yes – move $4 from buffer |
| Holiday exchange | $20 all-in | — | No |

Correct a small overage while it is still small
If one gift runs $4 over, take $4 from the buffer or reduce a later line by $4. Do not hide it. If several lines keep running over, the plan may be missing tax and wrapping, or the ceilings may not match how you actually shop.
Revise the categories without raising the annual total unless your wider budget has genuinely changed.
Let unused money remain unused
At year’s end, keep the balance for next year, return it to savings, or deliberately assign it elsewhere. Do not shop merely to make the column reach zero.
The quiet success of a gift budget is not that it purchased the maximum number of things. It is that the people you love were remembered and your ordinary life remained steady afterward.
A good gift plan leaves something behind
At the end of the year, the best sign that your plan worked may be wonderfully uneventful: the important people were remembered, the bills were still paid, and January did not arrive carrying December’s generosity on a credit card statement.
Some gifts will cost less than expected. One may run a little over. Another occasion may need only a card and a few honest words. Let the plan bend when life changes, but do not let guilt quietly raise the annual ceiling. Care does not become more convincing because it leaves you short of money.
That is how to plan gifts on a tight budget without turning every celebration into a negotiation with your bank account: see the year, choose the ceiling, save a little at a time, count the whole cost, and stop when the money is gone.
A thoughtful gift should leave the recipient feeling remembered – and leave the giver able to breathe afterward.